

The Trump administration finalized a new regulation governing student loans back in July. At the time, it didn’t receive much attention outside of the higher-education specialty press, though the New Republic did publish an alarmist writeup of the change. The New Republic piece also did not receive much attention at the time.
Recently, though, the piece got quite a bit of attention when they re-promoted it with a tweet warning that under the new rule, “degrees for social work, art, religious studies, teaching aides, and music will be hit the hardest.”


I responded briefly on Twitter that making it harder for schools to build a business model around nonperforming loans is a good idea that originated in the Obama administration and, for my trouble, got roundly dunked on as an enemy of the poor and a hater of the liberal arts. Former Congressman Max Rose called me “a real A Hole,” and a whole bunch of folks mocked me for having studied philosophy.
But what we’re seeing here is the power of framing and negative partisanship.
The actual rule the Trump administration is implementing sets an extremely low bar for institutions to clear, asking essentially that graduates of a program have earnings that are, on average, higher than the earnings of people who don’t have a degree at all. So for an undergrad program, the test is “do you earn more than people who only finished high school?” and for a master’s program, the test is “do you earn more than people who only finished college?”
Philosophy majors actually have high earnings on average compared with other college graduates, so we’re light-years from barring loans to students studying philosophy. More broadly, though, every liberal arts program from every even remotely selective college easily clears this bar.
I was recently at Middlebury College, where you can take courses in not-so-lucrative fields like “food studies.” But while some like to poke fun at people who spend four years in college to get a humanities degree that does not have obvious labor-market value, it is in fact the case that the people who complete those degrees earn more on average than the average American with no college degree.
The actual targets here are overwhelmingly programs at the very low end of the American higher-education pyramid.
About 55 percent of students in programs that would, as currently structured, flunk the test are at for-profit colleges. By enrollment, the largest fields that are going to lose out are things like certificate programs in cosmetology and culinary services.
Most of all, though, you have to understand that Trump’s rule is simply replacing a similar Biden administration rule, which itself was recapitulating an Obama-era regulatory effort. Trump has broadened the scope somewhat while also setting a somewhat weaker standard. I think reasonable people can disagree as to whether the Biden rule or the Trump rule is better all things considered, but fundamentally, they’re not that different, and the main problem is that neither quite goes far enough.
The federal government should not be subsidizing higher-education scams!
The fraught history of student loan regulation
A core problem with almost all discussions of higher-education policy is that 98 percent of the Discourse Class attended a selective college or university and is totally blind to the non-selective side of higher education that enrolls the majority of the students and is home to the vast majority of the problems.
This whole saga goes back to Obama’s first term, when the Department of Education decided it should put some teeth into legislative language stipulating that for vocational-education programs to be eligible for federally backed student loans, they needed to be preparing students for “gainful employment.” The department published a rule in 2011 that was aimed at cracking down on the worst-performing quarter of for-profit programs.
The targeted institutions were basically all for-profit colleges, and they vociferously opposed the measure, lobbying hard against Obama and also suing.
Republicans at the time perversely took the side of the for-profit colleges. There’s an unfortunate strain in American conservatism — also seen in the treatment of Medicare Advantage — that holds that it’s bad to spend money, but that as long as money is spent, it should be spent in a way that maximally aligns with predatory business interests.
Separate from the policy question, though, we had the legal issue of whether the administration really had the statutory authority to regulate in this way. And a federal judge ruled in 2012 that they did not:
Under the regulations, programs had to meet one of three tests or lose their eligibility for federal student aid: at least 35 percent of graduates must be repaying their loans, the typical graduate’s estimated annual loan payments must not exceed 12 percent of earnings, or they must not exceed 30 percent of discretionary income.
But Judge Contreras ruled that the 35 percent debt-repayment standard had no basis. “No expert study or industry standard suggested that the rate selected by the department would appropriately measure whether a particular program adequately prepared its students,” the opinion said. “Instead, the department simply explained that the chosen rate would identify the worst-performing quarter of programs. Why the bottom quarter? Because failing fewer programs would suggest that the test was not ‘meaningful’ while failing more would make for too large a ‘subset of programs that could potentially lose eligibility.’ ”
In an ideal world, Republicans would have just agreed that cracking down on bad student loans was a good idea, and the legislative process could have selected a nice, somewhat arbitrary round number — something Congress is really good at.
Obama won re-election and in 2014 published a new version of the rule, one that stood up against multiple lawsuits.
Then Donald Trump won the 2016 election.
In early 2017, we saw a novel legal theory from the American Association of Cosmetology Schools that argued that using Social Security Administration data to assess the earnings of their schools’ graduates was unfair because so many of their former students are cheating on their taxes by underreporting cash income. They actually won in court with this argument. The whole thing became largely moot, though, because new Education Secretary Betsy DeVos was a huge ally of the for-profit-college industry and immediately announced that she wouldn’t enforce the rule.
Her refusal resulted in a lot of litigation around non-enforcement and also about the administration’s efforts to formally rescind the rule, but in the fall of 2020, the Trump administration eventually prevailed in court and killed the rule.
Of course, right after that, Trump lost the election. Biden then came in and the whole rule-making process started over again. Initially, the Biden administration’s focus was student loan forgiveness, so it wound up taking all the way until fall of 2023 for a new version of gainful employment to get done. The rule they came up with was stricter than the old Obama-era rule because in addition to the debt-to-earnings ratio test, they also imposed an earnings premium test.
The main thing Trump’s new rule does is weaken the Biden rule by dropping the debt-to-earnings test. I know this is all pretty convoluted, but here’s a summary chart Claude made:
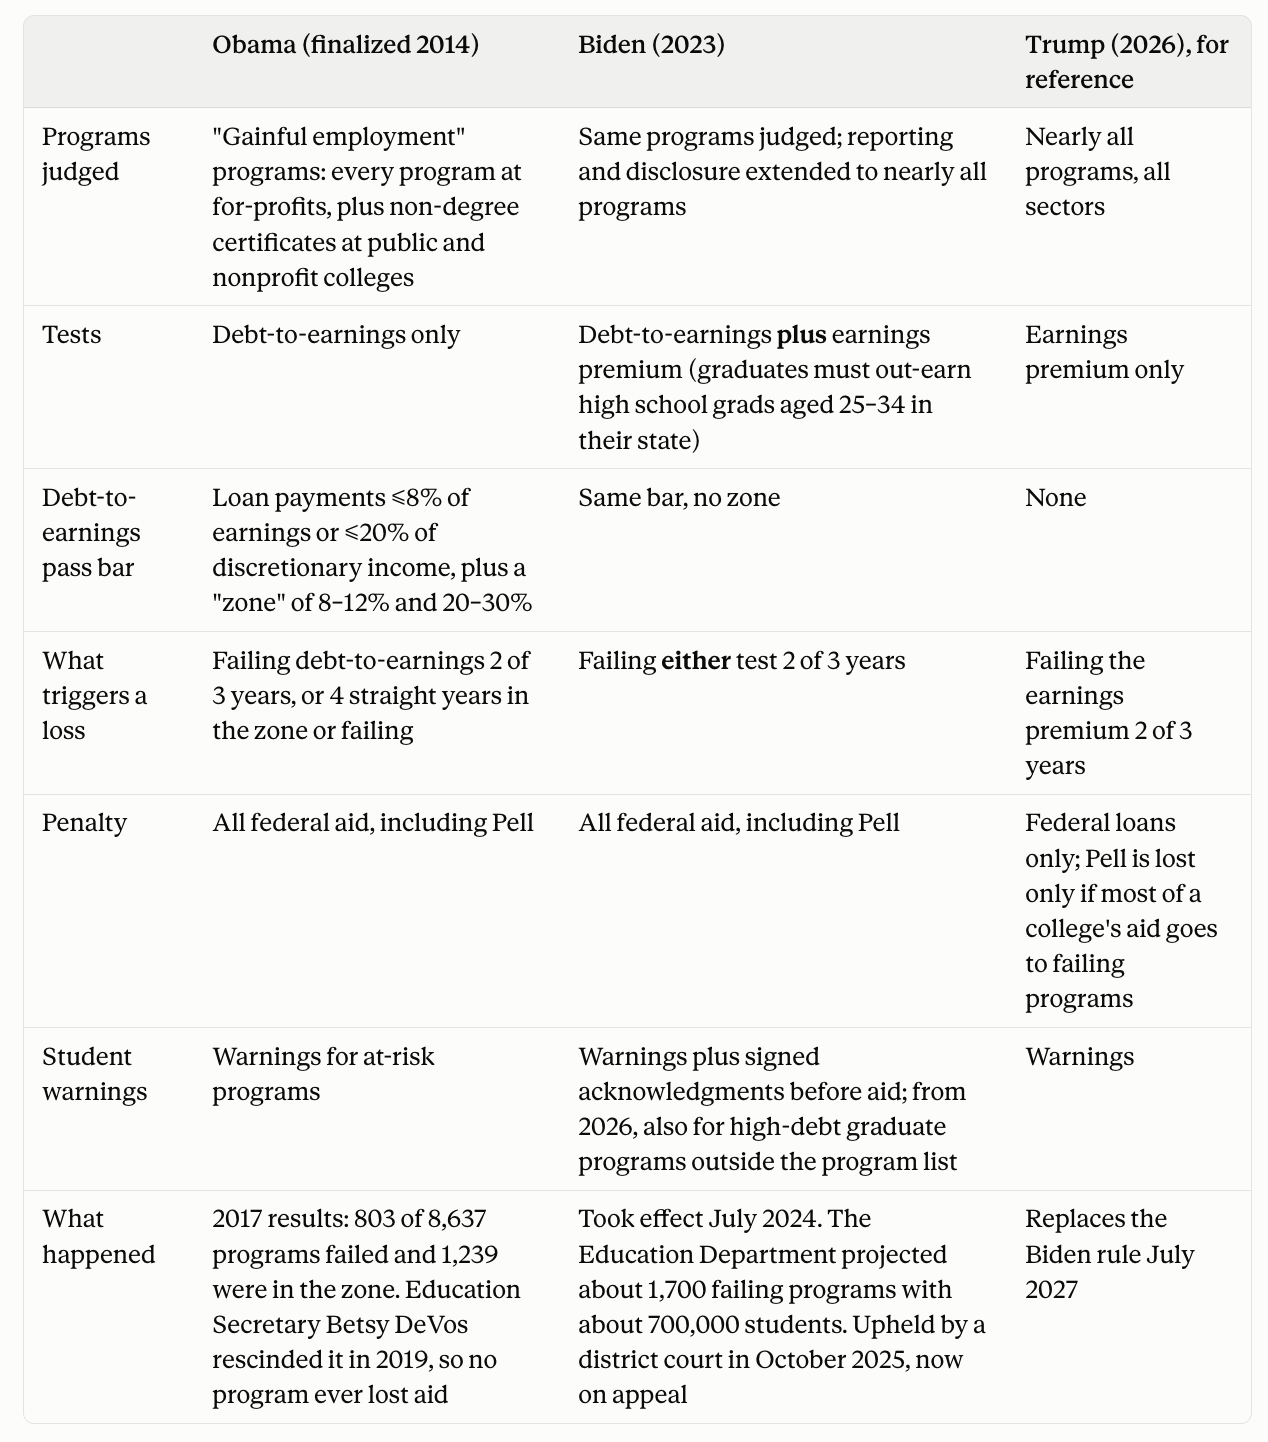
Trump did, however, strengthen the Biden policy in one respect: making it apply to all programs rather than only for-profits and non-degree certificates. In practice, this makes very little difference, and on net, there will be fewer failing programs under the Trump criteria than under the Biden criteria.
But it does perhaps explain why you see a progressive magazine denouncing it.
Trump is doing what he should have done in the first place
If you go back to Trump’s first term, the stated complaint about Obama’s regulations is that they were discriminatory against for-profit programs — a kind of protectionism for the traditional higher-education sector.
Some (though by no means all) people involved in making this policy in the Obama administration quietly agreed with that criticism. They felt that the administration, for political reasons, just decided it couldn’t take on the entire university sector. Their hope was that you could get something like the Obama rule in place and then eventually Republicans would level up by applying the same policy across the board.
Instead, they initially leveled down.
Trump’s second go-round as president has mostly been change for the worse. Relative to his first term, he’s been much more aggressive about abusing the powers of his office and has engaged in a much higher level of dangerous policy adventurism around everything from tariffs to Iran.
But in this case, we’re looking at an example of change for the better. He’s keeping in place the core of the Obama and Biden administration’s efforts around accountability for scam programs, and he’s addressing the discrimination concern by holding everyone to a standard rather than by eliminating the standard. It is true that this means a certain number of master’s degree programs in things like religious studies, mental health counseling, and studio art from nonprofit universities are going to be disqualified. But the vast majority of failing programs continue to be undergrad certificates or associate degree programs like cosmetology. That’s who was suing under Obama and Biden, that’s who was behind the bad policy of the first Trump term, and that’s who really loses out now that Trump is leveling up rather than leveling down.
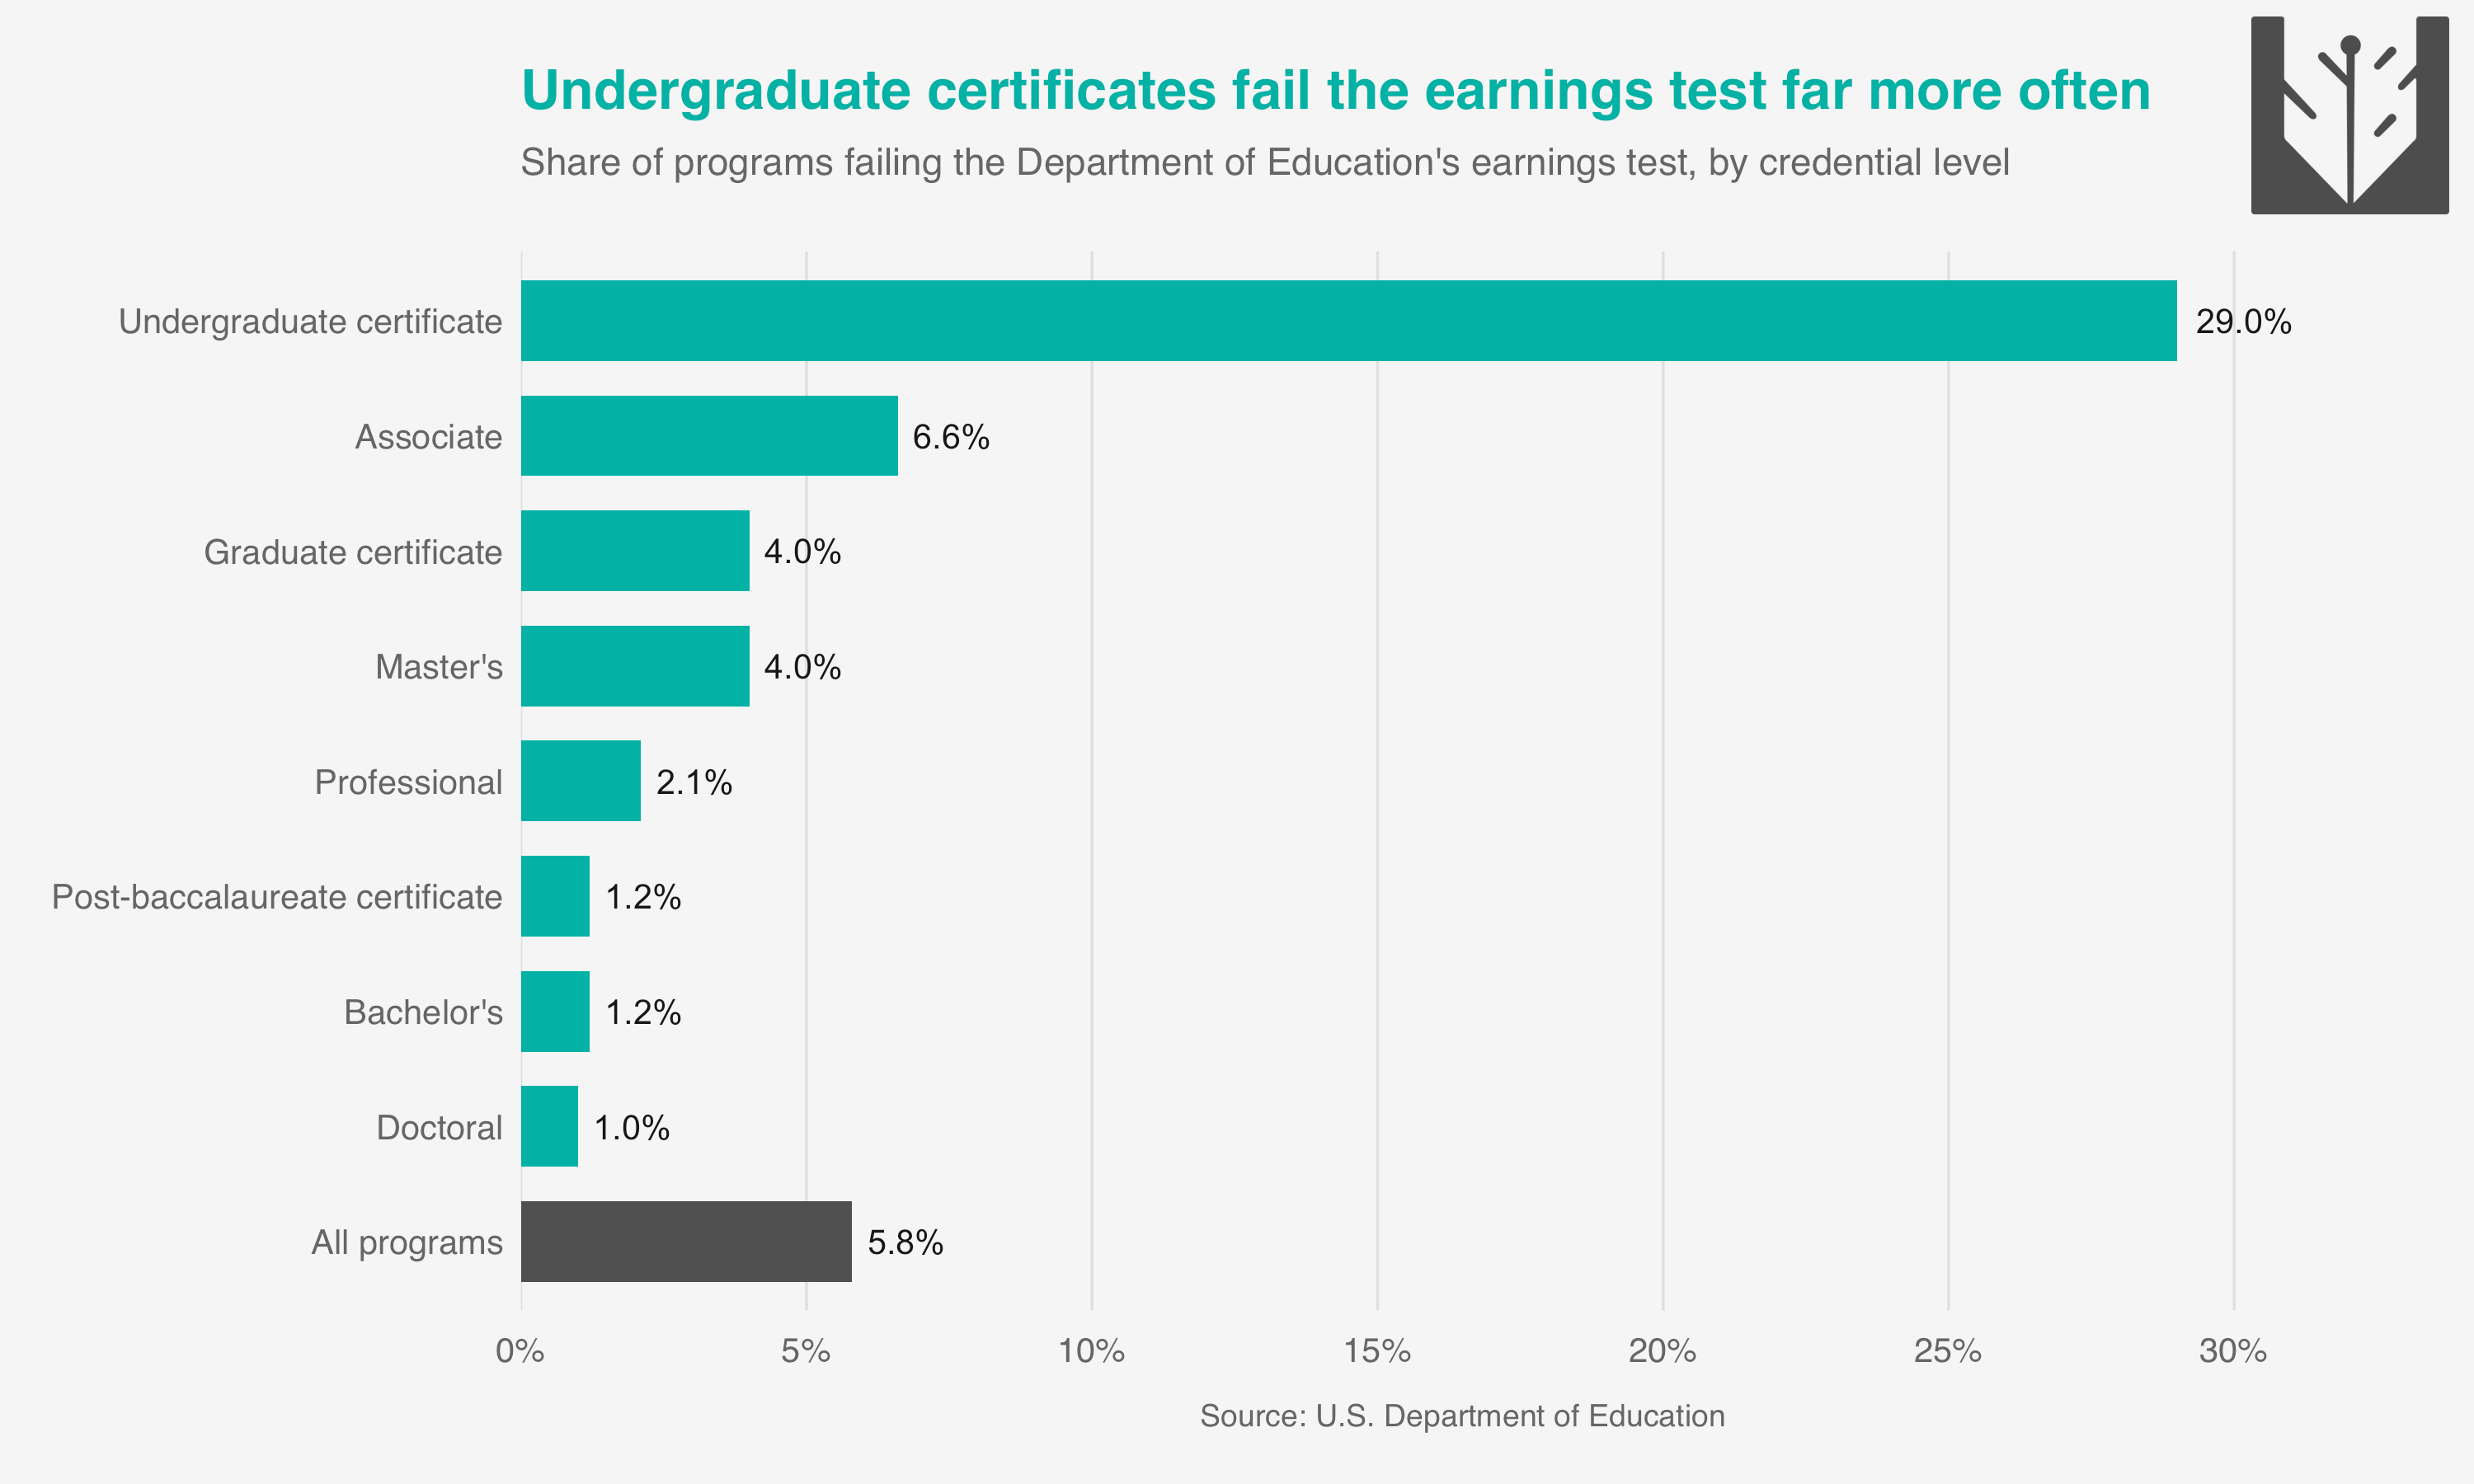
I suppose your mileage may vary as to whether it’s good for traditional nonprofit universities to run low-value master’s degree programs as a cash cow, but I think it’s pretty bad.
Of course, not everything in life is about money, and if schools want to make the case that someone (taxpayers, philanthropists, I dunno) should give them money to make cheap or free master’s degree programs for counselors, that’s fine. But you shouldn’t be able to use the federal student loan program as a back-door cash grab whether you’re for-profit or nonprofit.
The only problem with Trump’s rule is that he dropped Biden’s debt-to-earnings test.
Trump’s way of looking at it does nothing to distinguish cheap programs from expensive ones, which I think is a mistake. A certificate that costs $4,000 could be much more worthwhile than one that costs $40,000, even if the people who earn it make slightly less money than the people with the more expensive certificate.
Either way, though, all three versions of this rule have in fact been quite soft on the institutions they’re regulating. Nobody’s being asked to demonstrate that their programs have any causal benefit of any kind! All the government is asking for is the most naive earnings differential imaginable.
I’d be open to the argument that schools should be able to get out of hot water by showing some kind of non-monetary benefits to their students, but for that to make sense, you’d also want to ask questions about the causal impact of the program on earnings, which would be a much more rigorous bar to clear. It seems to me that America’s institutions of higher education are still getting off pretty easy here in terms of access to subsidized loans, and they ought to count their lucky stars rather than complaining.
So on Twitter social workers and education are really the center of the argument. And it’s frustrating because a few states really do require a master’s degree and have pay low enough that some people may fall behind the rule here.
I don’t really know how to make the state politics of public service more sensible. I mean I work with social workers as part of the foster system and they’re doing really awful work that does require a lot of knowledge about dealing with people in level ten crises and people meet the claims of low pay with they should just require an associate’s degree like it’s not a genuinely intellectually demanding field.
The requirement for master’s degrees in education seems quite silly especially in states that can’t hire enough teachers. New York and Pennsylvania both are rather difficult to get started in but pay well for careerists.
I don’t know how big of a problem the public service sector is but the program which is supposed to ameliorate this pslf is ran so poorly it was a nightmare to navigate under Trump 1. I eventually got loans forgiven but it took me something like 3 years of going back and forth with paperwork.
I love the genre of jurisprudence that amounts to “my client is innocent because he’s a scumbag”.